
Global markets are digesting a series of severe macroeconomic and geopolitical shifts this week. From direct naval hostilities in the Middle East pushing energy prices upward to physical resource limits appearing in the technology sector, the variables affecting global portfolios are compounding. For the herd at ElephantInvestor, navigating this environment requires strict due diligence and a focus on long-term capital preservation over reactionary trading.
Energy markets and maritime conflict
The conflict in the Middle East has escalated into direct naval hostilities between the United States and Iran in the Strait of Hormuz. Iranian forces captured a US unmanned submersible, and the United States responded with military strikes near Kharg Island, a primary node for Iranian crude exports. Concurrently, Houthi forces launched drone and missile attacks on Saudi Aramco petroleum depots in Jeddah and forced the shutdown of a major East-West crude pipeline.
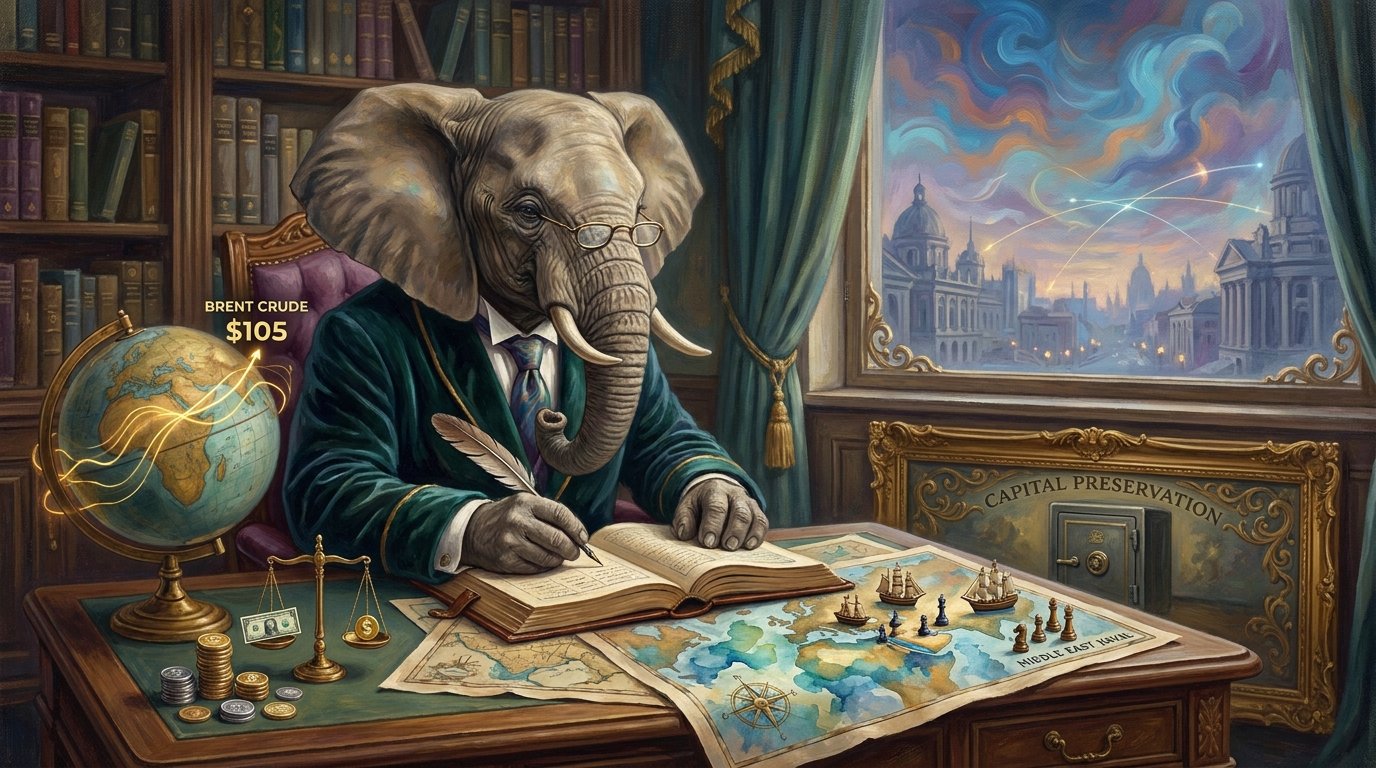
According to recent reports detailing the week’s escalations, these physical supply chain disruptions pushed Brent crude prices past $105 per barrel. High energy costs feed directly into consumer prices and manufacturing overhead. Investors analyzing this trend recognize that sticky inflation is highly probable when global shipping lanes and petroleum infrastructure are compromised. Market participants assessing energy markets must account for the reality that supply shocks are becoming structural rather than temporary.
Diplomatic realignments are also affecting regional economic stability. The United Kingdom suspended 30 arms export licenses to Israel. Alongside France and Canada, the UK imposed trade sanctions targeting Israeli settlement activities, stripping preferential trade terms for settlement-manufactured goods. These policy shifts introduce additional friction to Middle Eastern trade dynamics and require close monitoring by international investors.
Geopolitical realignments and currency markets
The BRICS nations met in New Delhi this week. India, China, and Russia issued a joint declaration focusing on reducing reliance on Western financial systems for international trade. This is a deliberate policy to bypass US dollar dominance in global settlements. For forex markets and emerging market portfolios, this transition introduces long-term macroeconomic changes. A gradual fragmentation of global trade settlements means Elephants analyzing international equities must account for currency risks and the development of alternative payment architectures.
The Russia-Ukraine conflict continues to demand high government defense expenditures. Russia deployed new jet-powered strike drones developed from Iranian munitions, while Canada committed to multi-year air defense aid for Ukraine’s energy grid. Defense contractors remain heavily engaged, and governments globally are expanding their military budgets. In a broader historical context, the United States marked the 25th anniversary of the September 11 attacks – a date that initiated massive, permanent changes in global defense spending and counter-terrorism infrastructure that continue to influence national budgets today.
Domestic policies and inflation risks
Political developments in Western nations are generating domestic economic uncertainties. In Germany, the Alternative for Germany party secured electoral victories in Thuringia and Saxony. This complicates regional governance and introduces volatility for the Euro, mirroring political gridlocks in France under the National Rally’s influence. Markets prefer stability, and fragmented parliaments often struggle to pass coherent fiscal policies or manage regional budgets efficiently.
In the United States, Donald Trump proposed a $1 trillion stimulus program. The plan includes $5,000 direct payments to citizens, funded entirely by aggressive new import tariffs. Economists note this combination is highly inflationary. Tariffs directly increase the cost of imported goods, while broad cash injections stimulate consumer demand. Portfolios heavily exposed to retail or import-dependent sectors may face severe margin compressions if these policies are enacted.
Technology bottlenecks and aerospace developments
The artificial intelligence sector is hitting physical resource limitations. Data centers require massive electricity and water inputs, leading to public protests and utility constraints across various municipalities. OpenAI reportedly paused the deployment of its newest models due to structural grid limitations and safety concerns. This indicates that future software growth is dependent on physical infrastructure. Long-term investment strategies often evaluate utility companies, grid modernization projects, and energy generation as necessary components of the artificial intelligence supply chain.
In the consumer electronics market, Apple entered the luxury foldable smartphone segment with a device priced at £1,999. This launch targets a high-end demographic that is generally insulated from broad consumer inflation, allowing the company to test price elasticity at the premium edge of the market.
The European aerospace sector is advancing its independent manufacturing and launch capabilities to replace lost Russian partnerships. A German startup successfully tested a hybrid-propulsion suborbital rocket, and France is leading negotiations for autonomous satellite communication networks utilizing the upcoming Ariane 6 launcher. These developments provide concrete capital expenditure targets in European industrial and aerospace equities.
Elephant Conclusions for the Herd
The current macroeconomic environment is defined by resource constraints and supply chain vulnerabilities. With crude oil breaking $105 per barrel and protectionist trade policies gaining political traction in the United States and Europe, inflation is positioned to remain sticky. The physical limitations of the AI sector further demonstrate that capital is flowing back toward tangible assets, utility grids, and physical infrastructure.
Patience remains the primary tool for the herd. Market volatility driven by Middle Eastern naval conflicts and European political fragmentation creates noise, but the underlying structural shifts are clear. Capital preservation in this environment requires accounting for sustained inflation, evaluating defense and aerospace allocations, and monitoring the BRICS coalition’s efforts to alter global currency dependencies. Elephants must maintain a long-term perspective and anchor their portfolios in sectors that demonstrate pricing power and physical necessity.
This article was generated by AI based on news reporting from the past week. Please perform your own due diligence before making investment decisions.